Deep Dive
来自我们记者的行业洞察
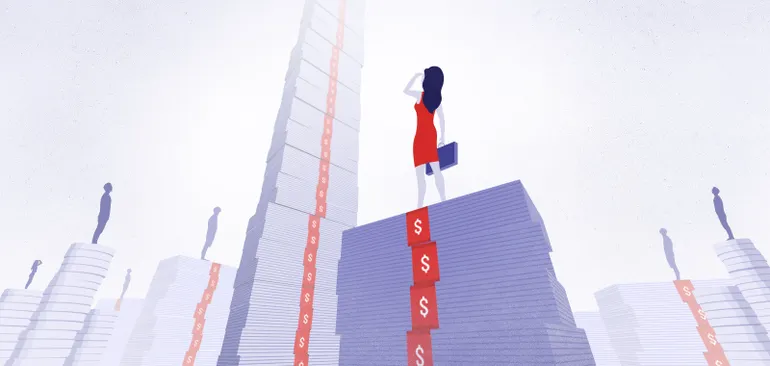
An analysis by BioPharma Dive of 180 leading biotech companies shows that only 15 were led by women in 2023, accounting for less than 10%. Veracyte CEO Bonnie Anderson called this figure "astonishingly low and absurd." BIO, the industry's main lobbying organization, has more than doubled its diversity committee budget but has not yet set a target for the proportion of female CEOs. Several industry executives have called for more proactive action.
Pharmaceutical companies are pursuing better-designed, lower-cost clinical trials, driving contract research organizations (CROs) to transform into data service providers. Over the past year, companies such as Thermo Fisher, Cambrex, and Charles River Laboratories have invested hundreds of millions of dollars to expand related businesses. Regulatory signals and the demand for real-world data are becoming key catalysts for this transformation.
A decade ago, Neurocrine was on the brink of collapse after its lead drug candidates were repeatedly rejected and funding ran tight, with staff slashed from nearly 600 to 67. Today, the San Diego-based biotech has two marketed drugs and a market cap of about $7.8 billion. In an exclusive interview, CEO Kevin Gorman looks back on the company's full journey from its founding in the late 1980s, its collapse in the 2000s, to its recent revival, while analyzing industry shifts, lessons from FDA collaborations, and the future competitive landscape.
Gene therapy is moving from the laboratory to the clinic, but issues such as high pricing, difficulties in medical insurance reimbursement, the complexity of treating polygenic diseases, and regulatory balance are testing the sustainability of this emerging field.
Estimates of the patient population and market potential for nonalcoholic steatohepatitis (NASH) are fraught with significant uncertainty. The National Institutes of Health estimates a prevalence rate of 3%-12% among U.S. adults, but the studies it relies on include fewer than 400 participants. Investment banks' market forecasts range from $7 billion to $20 billion, far below the $35 billion opportunity claimed by pharmaceutical companies. Diagnostic challenges, patient heterogeneity, and payer resistance make the commercialization of NASH drugs difficult.
As NASH drugs enter the final countdown to market launch, payer attitudes have become a key variable. Clinical data show that early drugs have limited efficacy, with annual treatment costs potentially reaching $10,000 to $18,000. Physicians and industry analysts expect payers to strictly limit reimbursement scope, prioritize coverage for patients with the most severe liver fibrosis, and may require liver biopsy as a precondition. The effectiveness of lifestyle interventions further weakens the cost-effectiveness argument for the drugs.
Although liver biopsy is the gold standard for diagnosing NASH, its invasiveness, high cost, and shortage of physicians may hinder the widespread use of future NASH drugs. The industry is seeking non-invasive alternatives.